Key Takeaways
- An FHA 203(k) loan finances a home purchase and renovation with a single mortgage.
- Borrowers use a 203(k) loan to repair, upgrade, or modernize a property.
- The Limited 203(k) covers up to $75,000 in nonstructural repairs. The Standard 203(k) handles larger or structural projects, requires at least $5,000 in eligible improvements and requires a 203(k) consultant.
- This loan helps buyers afford fixer-uppers that may not qualify for traditional financing.
An FHA 203(k) loan lets you buy or refinance a home that needs work and roll the repair costs into the same mortgage, with one monthly payment. The Limited 203(k) covers up to $75,000 in nonstructural repairs. The Standard 203(k) is for larger or structural projects and requires at least $5,000 in eligible improvements. Both follow FHA’s credit, down payment and occupancy rules, and the home must be your primary residence.
THINK YOU CAN BUY A HOUSE?
Prove it on The Homebuyer’s Trail — a free retro game with weekly $100 gift card drawings
In this article (Skip to...)
- What is an FHA 203(k) loan?
- How does the FHA 203(k) loan work?
- Types of FHA 203(k) loans
- What can an FHA 203(k) loan be used for?
- FHA 203(k) loan requirements for 2026
- Refinancing with a 203(k) loan
- Where to get an FHA 203(k) loan
- FHA 203(k) loan pros and cons
- Alternatives to an FHA 203(k) loan
- FHA 203(k) loans versus conventional home rehab loans
- How to get an FHA 203(k) loan
- FAQs about FHA 203(k) loans
- Final thoughts about the FHA 203(k) rehab loan
Want to see our expert mortgage insights first?
Add The Mortgage Reports as a preferred source on Google. You’ll automatically see our latest rate analyses, buying guides, and housing forecasts highlighted in your Google Search, AI Mode, and AI Overviews.
What is an FHA 203(k) loan?
An FHA 203(k) loan is a government-backed mortgage that lets you buy or refinance a fixer-upper and finance the repairs with a single loan and a single monthly payment. Often called a “rehab loan,” it solves a major problem for buyers because most lenders refuse to finance homes that need significant repairs. With a 203(k) loan, the lender tracks and verifies the renovation work, which makes it willing to approve financing on a property it would normally reject.
A property that does not currently meet FHA health, safety or security requirements may qualify if the approved rehabilitation will correct those problems. The completed improvements must meet applicable FHA property standards and local building codes. This program appeals to buyers who want an affordable way into homeownership and prefer improving a lower-cost home rather than paying more for a move-in-ready property.
Check your 203(k) loan eligibility. Start here
How does the FHA 203(k) loan work?
The FHA 203(k) loan works by combining the cost of the home and its renovations into one loan. Borrowers submit renovation plans, including contractor bids and timelines, which are reviewed by the lender. The home is then appraised to determine its current value and its projected value after renovations. Based on this, the loan amount is calculated, ensuring it falls within FHA loan limits.
Once approved, the funds for the home purchase are disbursed at closing, while renovation funds are held in escrow and released in stages as the work is completed. The Standard 203(k) allows up to 12 months to finish the work and the Limited 203(k) up to nine months, with inspections along the way to ensure the work is on track.
Fast Fact
An FHA 203(k) loan combines the home purchase and eligible repairs in one mortgage, but requires additional renovation documentation and oversight.
Types of FHA 203(k) loans
There are two types of 203(k) loan options: Standard 203(k) loans, also known as Full 203(k) loans, and Limited 203(k) loans, also called Streamline 203(k) loans. Both are federally insured mortgages for buying and remodeling a home. However, each one is customized for a specific project type, based on the scope and cost of the planned renovations.
| Loan variant | Repair cost limit | Minimum repair cost | 203(k) consultant | Eligible upgrades |
| Standard 203(k) | No separate cap; the total loan must fit within the FHA loan limit for your county | $5,000 in eligible improvements | Required | Major and structural renovations: roof, plumbing, foundation, additions, accessibility changes |
| Limited 203(k) | Up to $75,000 in total rehabilitation costs | No HUD minimum | Not required, but may be used | Minor nonstructural repairs and upgrades: paint, flooring, new appliances |
Standard FHA 203(k) Loans
Limited FHA 203(k) Loans
What can an FHA 203(k) loan be used for?
The work you can finance depends on the loan type: the Limited 203(k) is for minor, nonstructural repairs, and the Standard 203(k) also covers structural work.
Check your 203(k) loan eligibility. Start hereThe Standard 203(k) loan is ideal for major renovations and can be used for a wide range of repairs and upgrades. Here are some of the renovations you can finance with this loan:
- Major structural alterations
- Converting a single-family home into a 2-, 3- or 4-unit home, or vice versa
- Connecting to public sewer or water
- Larger landscaping projects
- Improving accessibility for disabled persons
- Moving the house to a different site
- Plus everything that the Limited loan can do
The Limited 203(k) loan is designed for smaller-scale repairs and renovations. It covers updates and repairs that don’t involve structural work, as long as the work won’t keep you out of the home for more than 30 days in total. Some eligible renovations include:
- Small kitchen and bathroom remodels
- Appliance replacement
- HVAC upgrades or replacements
- Carpet and flooring
- Roof replacement that doesn’t affect the home’s structure, plus siding, gutters and downspouts
- Painting
- Repairing health and safety hazards
- Energy-efficient home improvements
- Septic system improvements
While the FHA 203(k) loan can cover a wide range of renovations, certain luxury items and non-essential improvements are not eligible. Here’s what you can’t use the loan for:
- Luxury items such as new swimming pools, hot tubs, saunas or outdoor fireplaces. Repairing an existing in-ground pool is allowed.
- Non-permanent items such as satellite dishes, garden fountains, and barbeque pits.
Cosmetic improvements such as eligible painting and flooring may qualify; the project must comply with the selected 203(k) program’s eligible-work rules.
In these cases, other options might be a better fit, such as getting a home equity loan after purchase or other alternative rehabilitation loans.
Check your 203(k) loan eligibility. Start here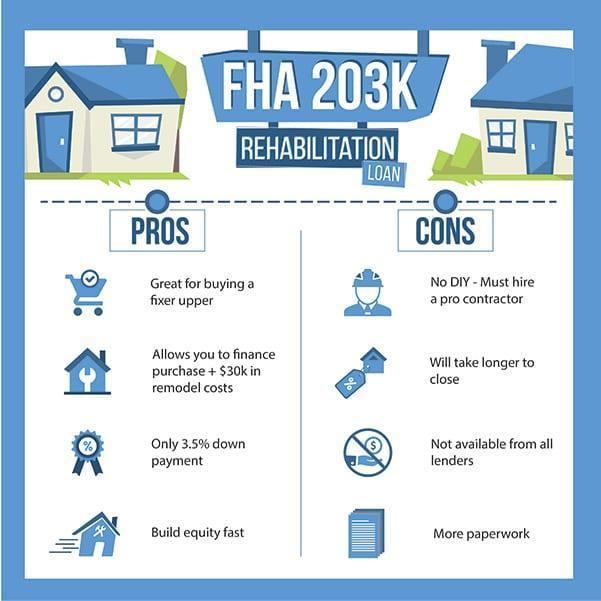
FHA 203(k) loan requirements for 2026
A 203(k) loan is a subtype of the popular FHA loan, which is meant to help those who might not otherwise qualify for a home loan. FHA 203(k) loans follow FHA credit, down payment and underwriting rules, along with additional renovation requirements. Eligibility requirements differ from conventional renovation programs, and lenders may impose additional requirements.
Verify your FHA 203(k) loan eligibility. Start hereHere’s a breakdown of the main eligibility requirements for an FHA 203(k) loan:
- Credit score requirements
- A credit score of 580 or higher qualifies for maximum FHA financing. Scores from 500 to 579 are limited to 90% loan-to-value, so you’d need at least 10% down.
- Lenders can set higher minimums of their own. Meeting a minimum credit score does not guarantee approval; property, equity and other underwriting requirements apply. Read more about FHA credit score requirements, or compare the requirements for conventional construction loans.
- Minimum down payment
- Eligible borrowers with credit scores of at least 580 may qualify with a 3.5% minimum down payment; scores from 500 to 579 require at least 10%. Lender requirements may be stricter.
- Illustratively, if FHA’s applicable purchase-and-rehabilitation calculation is $225,000 and the borrower qualifies for 3.5% down, the down payment is $7,875. Closing costs and other required funds are additional.
- Eligible gifts or assistance may help, subject to FHA and lender rules.
- Income and debt requirements
- Debt-to-income (DTI) ratio: For manually underwritten loans, FHA’s standard limits are 31% of qualifying income for housing expenses and 43% for total monthly debt payments. Borrowers with credit scores of at least 580 and two qualifying, documented compensating factors may be eligible for limits of 40% and 50%, respectively. Lender requirements may be stricter.
- At the standard 43% total-debt limit, $5,000 in qualifying monthly income allows $2,150 in total monthly debt payments, including the proposed mortgage payment.
- Meeting a minimum credit score does not guarantee approval; property, equity and other underwriting requirements apply.
- Maximum loan amount
- For a purchase, the maximum base mortgage is generally the applicable FHA loan-to-value percentage multiplied by the lesser of (1) the adjusted as-is value plus eligible financed repairs, fees and reserves, or (2) 110% of the after-improved appraised value; 100% for condos. The adjusted as-is value generally starts with the purchase price, less inducements to purchase, and cannot exceed an as-is appraisal when one is obtained. The base mortgage is also subject to the applicable FHA loan limit.
- Must stay within FHA loan limits for your county. For 2026, the one-unit FHA loan-limit floor is $541,287 and the standard high-cost ceiling is $1,249,125. Higher limits can apply in Alaska, Hawaii, Guam and the U.S. Virgin Islands; check the limit for the property’s location.
- Mortgage insurance premiums
- Upfront Mortgage Insurance Premium (UMIP): 1.75% of the loan amount, paid at closing.
- Annual Mortgage Insurance Premium (MIP): 0.15%-0.75% of the loan amount, divided monthly.
- Annual MIP generally lasts 11 years when the original loan-to-value ratio used for mortgage insurance is 90% or less, and for the mortgage term when it exceeds 90%. For a 203(k), FHA calculates this ratio by dividing the base loan amount by the after-improved appraised value.
- Occupancy and citizenship requirements
- Must use the property as a primary residence; not eligible for investment properties.
- Available to U.S. citizens, lawful permanent residents and citizens of the Federated States of Micronesia, the Marshall Islands and Palau.
Verify your 203(k) loan program eligibility. Start here
Refinancing with a 203(k) loan
You can also use a 203(k) loan to refinance a home you already own and add the cost of repairs to the new loan. The Standard and Limited rules still apply: a Standard 203(k) refinance needs at least $5,000 in eligible improvements, and a Limited 203(k) refinance can include up to $75,000 in total rehabilitation costs. An appraisal sets the home’s value after the planned improvements. The maximum refinance loan amount is the lowest of:
- Your existing mortgage debt plus the repair costs and the fees and reserves that can be financed
- The applicable FHA loan-to-value percentage multiplied by the lesser of (a) the adjusted as-is value plus eligible financed repairs, fees and reserves, or (b) 110% of the after-improved value; 100% for condos. Maximum financing is 97.75% for credit scores of at least 580 and 90% for scores from 500 to 579.
- The FHA loan limit for your county
The lender determines the adjusted as-is value under FHA’s refinance rules; it is not always a new appraisal of the home’s current value. Meeting a minimum credit score does not guarantee approval; property, equity and other underwriting requirements apply.
If you acquired the home less than 12 months before the loan’s case number is assigned, the lender must order an as-is appraisal and use that value, unless you inherited the home or received it as a gift from a family member. You do not need to have an existing FHA loan to qualify for an FHA 203(k) loan for refinancing.
Where to get an FHA 203(k) loan
You can obtain an FHA 203(k) loan through an FHA-approved lender, but not all lenders offer this program or have loan officers who understand how it works. Before applying, verify that the lender regularly underwrites 203(k) loans and has experience with the renovation process. The U.S. Department of Housing and Urban Development (HUD) offers an online search tool that allows you to check if a lender has completed at least one 203(k) loan in the past year. Enter the lender’s name in the search bar, scroll to the program list, and select the 203(k) rehabilitation mortgage insurance option to confirm their participation.
Check your home buying options. Start hereWhat experts are saying
Thomas Brock, CFA, CPA
“I’ve seen homebuyers get so focused on finding a lender that offers FHA 203(k) financing that they underestimate the importance of the contractor. With a regular home purchase, a contractor who runs late or underestimates a job is frustrating. With an FHA 203(k) loan, it can seriously disrupt the financing process because renovation money is held in escrow and released as work is completed and approved.
As a result, it’s critical to evaluate the contractor just as carefully as you evaluate the lender. Moreover, remember that the cheapest bid isn’t necessarily the best bid, especially if the contractor lacks the experience or financial capacity to drive the project through the draw process.”
FHA 203(k) loan pros and cons
You can find inexpensive fixer-uppers that require updating or repairs, and the repairs themselves might not cost much. For example, a house that could be worth $250,000 might sell for only $200,000 when it requires just $20,000 in repairs. That leaves $30,000 in potential equity for a buyer with the initiative to manage the fixes.
Verify your 203(k) loan program eligibility. Start hereStill, this strategy isn’t right for everyone.
FHA 203(k) pros
- Instant equity potential: Purchase a property below market value and gain equity after repairs are complete.
- Less competition: Fewer buyers are interested in homes needing repairs, which can make purchasing easier.
- Remodeling experience: Gain hands-on experience with home remodeling, adding to your homeowner skills.
FHA 203(k) cons
- Mortgage insurance costs: You pay an upfront premium of 1.75% plus an annual premium. Annual MIP generally lasts 11 years when the original loan-to-value ratio used for mortgage insurance is 90% or less, and for the mortgage term when it exceeds 90%. For a 203(k), FHA calculates this ratio by dividing the base loan amount by the after-improved appraised value.
- Contractor requirements: Contractors must meet local licensing and bonding rules and document every repair. Doing work yourself needs the lender’s approval, and you’re reimbursed for materials only.
- Bid revisions: Lenders may require multiple bid revisions with the contractor for approval.
- Upfront repair decisions: Must decide on repairs and stay within budget before finalizing the loan.
- Extended loan process: Requires more paperwork than a standard FHA loan, including contractor bids and an appraisal based on the planned work, so closing usually takes longer. Set realistic timelines with the seller.
What experts are saying
Thomas Brock, CFA, CPA
“One mistake I’ve seen homeowners make with renovation financing is assuming the contractor’s initial estimate is going to be the final cost. That can be dangerous, especially with an older home, where all kinds of significant structural issues can arise. An FHA 203(k) loan gives you a framework for handling renovation costs, but it doesn’t eliminate the risk that the project will cost more than expected.
So, view the renovation estimate as a starting point, not a guarantee. Additionally, scale back on cosmetic work and leave some flexibility in your renovation budget. Addressing unexpected electrical, plumbing or structural problems is much easier when you’ve left some room in the budget rather than committing every available dollar from the outset.”
Alternatives to an FHA 203(k) loan
An FHA 203(k) may not fit if you need only a few thousand dollars for minor work, your project includes luxury items FHA won’t finance or your total loan would exceed the FHA limit for your county. It may also not fit if you want mortgage insurance you can cancel. Annual MIP generally lasts 11 years when the original loan-to-value ratio used for mortgage insurance is 90% or less, and for the mortgage term when it exceeds 90%. For a 203(k), FHA calculates this ratio by dividing the base loan amount by the after-improved appraised value.
Verify your FHA 203(k) loan eligibility. Start hereOther home improvement loans and fixer-upper loans include:
FHA 203(k) loans versus conventional home rehab loans
Conventional home rehabilitation loans, such as Fannie Mae’s HomeStyle and Freddie Mac’s CHOICERenovation, and FHA 203(k) loans both finance a home purchase and its renovation in one mortgage. They differ most on credit requirements, property types, loan limits and mortgage insurance. For more detail, see this HomeStyle vs. FHA 203(k) comparison.
| Conventional rehab loans | FHA 203(k) loans | |
| Origination | Private lenders, no specific government backing. | Backed by the Federal Housing Administration. |
| Eligibility | Credit, debt-to-income and down-payment requirements vary by program and lender; eligible HomeStyle purchases may allow 3% down. | FHA credit and underwriting rules apply; eligible borrowers may qualify with 3.5% down. Lenders may impose additional requirements. |
| Property restrictions | Flexible property types. | One-to-four units, at least a year old. |
| Loan limits | Typically higher. | Set by county, based on local home prices. |
| Renovation restrictions | Upgrades that add value. | Eligible repairs and improvements, including cosmetic upgrades; structural work requires Standard 203(k). |
| Mortgage insurance | PMI required < 20% down; can be removed once equity is built. | Upfront premium of 1.75% plus an annual premium. Annual MIP generally lasts 11 years when the original loan-to-value ratio used for mortgage insurance is 90% or less, and for the mortgage term when it exceeds 90%. For a 203(k), FHA calculates this ratio by dividing the base loan amount by the after-improved appraised value. |
How to get an FHA 203(k) loan
Applying for a 203(k) loan is a multi-step process that involves a bit more paperwork and time than a standard loan application due to the additional requirements related to the renovation plans.
Verify your FHA 203(k) loan eligibility. Start hereHere’s a detailed look at the steps involved:
1. Choose your home improvement projects
The first step of an FHA 203(k) loan is deciding which home improvements or modernizations you want to do (see the list of eligible renovations). The lender will require any safety or health hazards to be addressed first, including repairs like mold, broken windows, derelict roofing, lead-based paint, and missing handrails.
From there, you choose which cosmetic improvements you want to take care of, such as updating appliances, adding granite countertops in the kitchen, or installing a new bathroom. These types of updates are all eligible uses for this remodel loan.
2. Determine your eligibility
Make sure you meet the eligibility criteria for a 203(k) loan. FHA allows maximum financing with a credit score of 580 or higher, though lenders can set higher minimums, and manually underwritten loans start with a 43% limit on total debt-to-income. Meeting a minimum credit score does not guarantee approval; property, equity and other underwriting requirements apply. The property must be a one- to four-unit home that was completed at least one year earlier.
3. Find a suitable property and plan your renovations
Search for a property that you’d like to buy and renovate. Make a detailed plan of the improvements you wish to make, including cost estimates. For a Full 203(k) loan, your plan must involve at least $5,000 worth of renovations, while a Streamline 203(k) loan must not exceed $75,000 in total rehabilitation costs.
4. Choose your contractors
The next step is to find contractors. They must meet local licensing and bonding requirements, and the lender reviews each contractor’s credentials, work experience and references. You can do some of the work yourself only with the lender’s approval, and you’ll need to be a licensed general contractor or show experience completing rehab projects. You’re reimbursed for materials, not your own labor.
The best results will come from experienced and professional remodeling firms that have done at least one 203(k) renovation in the past. Be aware that one contractor’s refusal to complete the required forms could delay your entire project. So you might even go so far as to write the 203(k) paperwork requirements into the contractor agreement.
5. Get your bids
Once your contractor is on board with helping you complete your loan application, get official bids. Make sure the bids aren’t guesses. They must be completely accurate because the lender will submit final bids to the appraiser, who builds the value of the work into the future value of the property, upon which your loan is based.
Changing bid dollar amounts later could incur additional appraisal costs and trigger a re-approval with the lender. Again, make sure your contractor knows all this!
6. Choose a 203(k)-approved lender and provide documentation
Not every lender offers 203(k) loans, so it’s important to find a lender who is familiar with the specifics of the 203(k) loan process. You can find a list of approved lenders on the Department of Housing and Urban Development (HUD) website.
You will need to provide a range of documentation to support your application. This may include pay stubs, W-2s, tax returns, details about your debts, and a written proposal for your planned renovations.
7. Property appraisal and feasibility study
For a Full 203(k) loan, the lender selects an FHA-approved 203(k) consultant who inspects the property and prepares a work write-up and cost estimate for each repair. The improvements must meet HUD’s Minimum Property Requirements and local building codes. A feasibility study is optional and is done only when needed to decide whether the project makes sense. For a Streamline 203(k), a consultant isn’t needed, but the property still needs an FHA appraisal based on the planned work.
8. Closing the loan
Once the loan is approved, you’ll proceed to closing, where you’ll sign all of the loan documents. The renovation funds from your loan will be put into an escrow account to be released as work is completed.
9. Overseeing renovation work
Work should begin soon after the loan funds. If it hasn’t started within 30 days of the disbursement date, or stops for more than 30 days in a row, the lender may treat the loan as in default. The Standard 203(k) allows up to 12 months to finish and the Limited 203(k) up to nine months, unless the lender approves an extension. For a Full 203(k) loan, you’ll work with your consultant to oversee progress.
Depending on the extent of the repairs, you may be able to move in at the same time. But for bigger projects, arrange to live somewhere else until work is complete. With a Standard 203(k), you can finance up to 12 months of mortgage payments for the time you can’t live in the home, as long as it doesn’t exceed the time allowed to finish the work. The Limited 203(k) doesn’t allow this.
10. Move into your renovated home
Once the work is finished and the final inspection is approved, you can settle into the renovated home. Later, if you qualify for a conventional loan, refinancing may let you drop FHA’s mortgage insurance premium (MIP) that comes with the loan.
FAQs about FHA 203(k) loans
Check your FHA 203(k) loan options. Start here
Final thoughts about the FHA 203(k) rehab loan
It’s always wise to shop around for best mortgage lender. But with a 203(k) loan, you may not always want the lender with the lowest interest rate.
It’s often better to accept a higher interest rate if it’s coming from a lender with more 203(k) loan experience than the lender who’s offering a lower rate. This is a rare exception in mortgage shopping, in which the lowest rate may not be in your best interest.
In the world of 203(k) loans, contractor and lender experience is typically more of a consideration than cost. Click the link below to begin your search for the best FHA 203(k) loan lender for your financial needs.
Time to make a move? Let us find the right mortgage for you

