Mortgage rate forecast for next week (Sep 21 - 25)
Mortgage rates rose for a fourth straight week, marking four consecutive weekly gains.
The average 30-year fixed rate mortgage (FRM) increased to 6.95% on September 17, 2026 from 6.76% the prior week, according to Freddie Mac.
The 30-year fixed-rate mortgage continues to fluctuate as markets assess economic data. .share-container, #share-arrow
| Average 30-year fixed rate | 1-week ago | 4-weeks ago | 3-months ago | 1-year ago |
| 6.95% | 6.76% | 6.65% | 6.47% | 6.35% |
The latest borrowing activity
The 30-year fixed sits at 6.66%, matching where it stood four weeks ago at 6.66%.
Three months ago, the 30-year fixed averaged 6.53%, so rates are modestly higher than that point.
Find your lowest mortgage rate. Start hereOne year ago, the same rate stood at 6.56%, roughly 10 basis points below the current reading.
That leaves borrowers in a market that has drifted within a narrow band over the past several weeks.
- Will rates go down in September?
- 90-day forecast
- Expert rate predictions
- Mortgage rate trends
- Rates by loan type
- Mortgage strategies for September
- Mortgage rates FAQ
Will mortgage rates go down in September?
The 30-year fixed rate holds at 6.95%, near the top of its recent range after a 19 basis point jump from the prior week. With no FOMC meeting scheduled until late October, the calendar offers little to push rates sharply in either direction this month.
- Dave Meyer, Chief Investment Officer at BiggerPockets
Want to see our expert mortgage insights first?
Add The Mortgage Reports as a preferred source on Google. You’ll automatically see our latest rate analyses, buying guides, and housing forecasts highlighted in your Google Search, AI Mode, and AI Overviews.
Two data releases stand out for September. The CPI report arrives September 10, and the PCE report follows on September 25. Both give the market fresh readings on inflation, which is a key input for the direction of mortgage rates.
Absent a significant surprise in that inflation data or in the labor market, rates are likely to stay broadly flat through the rest of September. The next FOMC meeting on October 27-28, 2026 will be the next major policy signal.
For September, rates look likely to stay broadly flat to modestly lower. They are expected to hold above the major housing authorities’ 6.400% Q2 2026 quarterly-average forecast rather than fall to that level within the month.
Expert mortgage rate predictions for September
Andrew Dehan, Senior Analyst at Bankrate
Lenders base rates not just on your personal financial profile or the current market, but also on their business needs
Ted Rossman, Senior Industry Analyst at Bankrate
I expect the average 30-year fixed rate to fall below 6% for the first time since the summer of 2022
Mortgage interest rates forecast next 90 days
The Federal Reserve held its policy rate steady at its April 29, 2026 meeting. The next FOMC meeting is set for October 27-28, 2026, so no Fed policy change will occur during September itself.
Inflation readings will drive much of the near-term action. The CPI release on September 10 comes from the Bureau of Labor Statistics, and the PCE release on September 25 comes from the Bureau of Economic Analysis. Softer numbers could ease pressure on rates, while hotter numbers could push them higher.
Find your lowest mortgage rate. Start hereBorrowers should watch both reports closely and mark the October 27-28 FOMC meeting on the calendar. Those three events form the main catalysts for rate movement over the next 90 days.
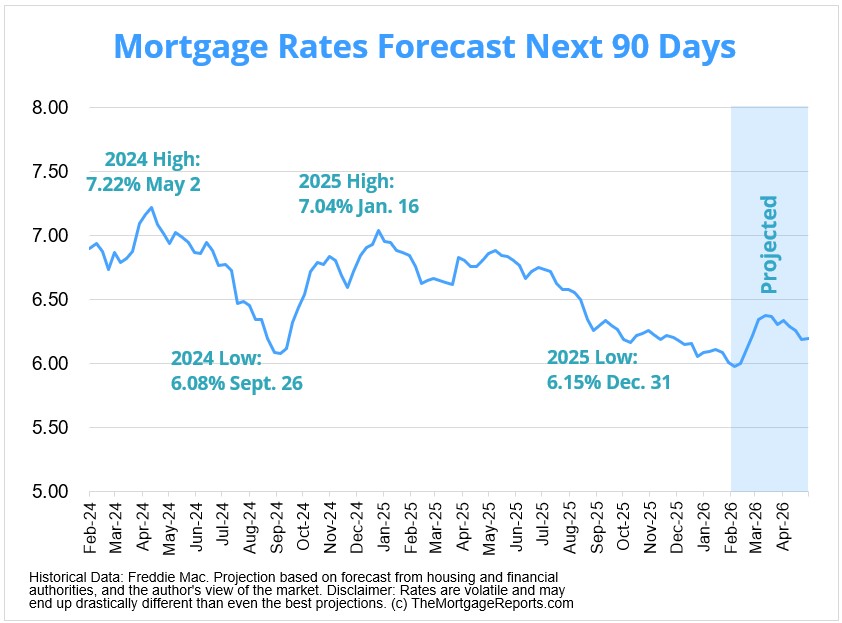
Mortgage rate predictions for September 2026
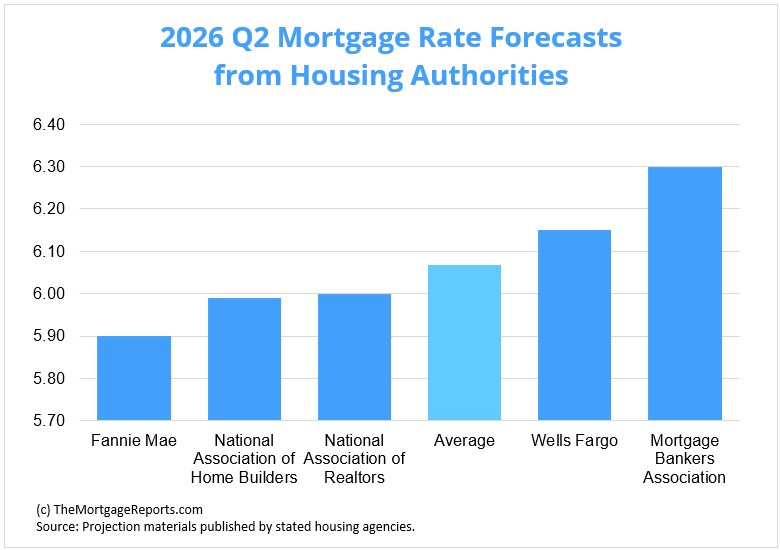
The major housing authorities published Q2 2026 quarterly-average forecasts for the 30-year fixed rate. Fannie Mae and the Mortgage Bankers Association both projected 6.40%, for an average of 6.40%.
These are projections for the Q2 2026 quarterly average, not September monthly figures, and they offer only loose directional context here.
| Housing Authority | 30-Year Mortgage Rate Forecast (Q2 2026) |
| Fannie Mae | 6.40% |
| Mortgage Bankers Association | 6.40% |
| Average Prediction | 6.400% |
Current mortgage interest rate trends
Freddie Mac reported the 30-year fixed rate at 6.95% on September 17, 2026. The 15-year fixed rate stood at 6.26% on the same date.
The 30-year rate rose from 6.76% the prior week, a gain of 19 basis points. That marks a notable move higher over a single week.
Looking back further, the 30-year rate was 6.66% four weeks ago. The recent climb has pushed it above that level.
| September 2026 | 6.95% |
| August 2026 | 6.66% |
| July 2026 | 6.66% |
| June 2026 | 6.49% |
| May 2026 | 6.53% |
| March 2025 | 6.65% |
| April 2025 | 6.73% |
| May 2025 | 6.82% |
| June 2025 | 6.82% |
| July 2025 | 6.72% |
| August 2025 | 6.59% |
| September 2025 | 6.35% |
| October 2025 | 6.25% |
| November 2025 | 6.24% |
Source: Freddie Mac
Three months ago, the rate sat at 6.53%. One year ago it was 6.56%, so the current 6.95% reading is higher than where rates traded across those earlier periods.
For a longer view of how rates have moved over the years, see our guide to the 30-year mortgage rate history.
The near-term trajectory hinges on the September inflation reports and the late-October FOMC meeting. Until then, the current 6.95% level reflects a market waiting for its next clear signal.
Mortgage rate forecast by loan type
Loan-type trends were mixed this week, with 30-year fixed at 6.95% and 15-year fixed at 6.26%.
Find your lowest mortgage rate. Start here30-year fixed
The 30-year fixed averaged 6.66% in Freddie Mac’s August 27 survey. It remains the most common choice for buyers who want a predictable payment spread over a long term.
If you plan to stay in the home for many years, the stability of a fixed payment can be worth the higher rate compared with shorter terms. Compare offers from several lenders before you commit.
The 15-year fixed averaged 5.98% in the same survey, below the 30-year rate. The tradeoff is a higher monthly payment in exchange for less interest paid over the life of the loan.
This term can suit borrowers with room in their budget who want to build equity faster. Run the numbers on the monthly payment before deciding.
Jumbo loans exceed conforming loan limits and often carry different pricing than standard loans. Lenders may apply stricter credit and reserve requirements.
If you are financing a higher-priced home, request quotes specific to jumbo programs. Pricing can differ meaningfully from lender to lender.
Mortgage rate strategies for September 2026
With the 30-year rate at 6.95% and no FOMC meeting until late October, rates are likely to hold broadly flat through September. That backdrop shapes how borrowers might approach their decisions this month.
Find your lowest mortgage rate. Start hereThe September CPI report on September 10 and the PCE report on September 25 are the main events that could move rates. A surprise in either direction could shift pricing quickly.
Given that setup, the strategies below focus on managing timing, refinancing, home buying, and credit under current conditions.
With the 30-year rate at 6.95% after a 19 basis point jump, locking protects against further upward moves. A lock secures your rate for a set period while you close.
Rate lock strategy
If you are close to closing, a lock removes uncertainty around the September inflation reports. Ask your lender about float-down options in case rates ease before you close.
Refinancing makes sense when the new rate saves enough to justify the closing costs within your expected time in the home. Run the numbers against your current rate and loan balance.
With rates near the top of their recent range, some borrowers may wait for a clearer signal from the September and October data. Others with a much higher existing rate may find savings available now.
Buyers face a 30-year rate of 6.95% this month. Getting preapproved helps you understand your budget and act quickly when you find the right home.
Because rates could shift on the September inflation data, build some flexibility into your payment expectations. Compare offers from multiple lenders before committing.
Refinance timing
Your credit profile directly affects the rate a lender offers. Strengthening it before you apply can lower your cost.
Focus on these steps to improve your standing before applying.
Pay down credit card balances to lower your utilization | Avoid opening new credit accounts before you apply | Check your credit reports and dispute any errors | Make all payments on time in the months leading up to your application
As Andrew Dehan noted, “Lenders base rates not just on your personal financial profile or the current market, but also on their business needs,” so shopping around still matters even with strong credit.
Home buying strategy
Small improvements in your score can translate into a better rate offer. Give yourself time to make these changes before you apply.
Combine strong credit with multiple lender quotes to put yourself in the best position this month.
- Your credit score and credit history
- Your personal finances
- Your down payment (if buying a home)
- Your home equity (if refinancing)
- Your loan-to-value ratio (LTV)
- Your debt-to-income ratio (DTI)
To figure out what rate a lender can offer you based on those factors, you have to fill out a loan application. Lenders will check your credit and verify your income and debts, then give you a ‘real’ rate quote based on your financial situation.
You should get three to five of these quotes at a minimum, then compare them to find the best offer. Look for the lowest rate, but also pay attention to your annual percentage rate (APR), estimated closing costs, and ‘discount points’ — extra fees charged upfront to lower your rate.
This might sound like a lot of work. But you can shop for mortgage rates in under a day if you put your mind to it. And shaving just a few basis points off your rate can save you thousands.
Compare mortgage and refinance rates. Start here
Mortgage interest rate FAQ
What are today’s mortgage rates?
Mortgage rates are rising, but borrowers can almost always find a better deal by shopping around. Connect with a mortgage lender to find out exactly what rate you qualify for.
Time to make a move? Let us find the right mortgage for you1Today's mortgage rates are based on a daily survey of select lending partners of The Mortgage Reports. Interest rates shown here assume a credit score of 740. See our full loan assumptions here.
Selected sources:
- https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
- http://www.freddiemac.com/research/datasets/refinance-stats/index.page