Mortgage rate forecast for next week (Nov 2 - 6)
Mortgage rates fell.
The average 30-year fixed rate mortgage (FRM) declined to 7.24% on October 29, 2026 from 7.32% the prior week, according to Freddie Mac.
The average 30-year fixed-rate mortgage remained unchanged this week,
| Average 30-year fixed rate | 1-week ago | 4-weeks ago | 3-months ago | 1-year ago |
| 7.24% | 7.32% | 7.28% | 6.66% | 6.19% |
The latest borrowing activity
The 30-year fixed sits at 6.66%, matching where it stood four weeks ago at 6.66%.
Three months ago, the 30-year fixed averaged 6.53%, so rates are modestly higher than that point.
Find your lowest mortgage rate. Start hereOne year ago, the same rate stood at 6.56%, roughly 10 basis points below the current reading.
That leaves borrowers in a market that has drifted within a narrow band over the past several weeks.
- Will rates go down in November?
- 90-day forecast
- Expert rate predictions
- Mortgage rate trends
- Rates by loan type
- Mortgage strategies for November
- Mortgage rates FAQ
Will mortgage rates go down in November?
Want to see our expert mortgage insights first?
Add The Mortgage Reports as a preferred source on Google. You’ll automatically see our latest rate analyses, buying guides, and housing forecasts highlighted in your Google Search, AI Mode, and AI Overviews.
The Federal Reserve held the federal funds rate at 3-3/4 to 4 percent at its October 27-28 meeting. The next decision is not due until December 8-9, which leaves bond markets to react mainly to incoming economic data through November.
Two reports stand out on the November calendar. CPI releases on November 12 and PCE releases on November 25. Both land before the December FOMC meeting and will shape expectations for that decision.
Our base case for November is a holding pattern consistent with the housing authorities’ Q4 2026 quarterly-average forecast of 7.350%, with modest downside if the November inflation prints come in softer than expected.
What experts are saying about mortgage rates
Sam Khater, Chief Economist at Freddie Mac
The average 30-year fixed-rate mortgage declined this week, offering some relief to prospective homebuyers,
Lawrence Yun, Chief Economist at National Association of Realtors
Despite the small monthly gain on a seasonally adjusted basis, August and September marked the two slowest months for home sales this year,
Lisa Sturtevant, Chief Economist at Bright MLS
Slightly lower rates and slower price growth should improve affordability a little, which could bring more buyers into the market,
Federal Reserve FOMC, Federal Open Market Committee at Federal Reserve
Prediction: Rates will hold steady
October 28, 2026 Federal Reserve issues FOMC statement For release at 2:00 p.m. EDT Share —> —> —> —> —> —> The Federal Open Market Committee approved the following statement for release by a 10 – 2 vote: The Committee decided to maintain the target range for the federal funds rate at 3-3/4 to 4 percent, in support of the Federal Reserve’s dual mandate. The Committee is continuing its policy of maintaining ample reserves in the banking system.
Ken Johnson, Finance Professor at the University of Mississippi
The recent panic in the bond market is subsiding with the 10-year Treasury settling around 5.0%,
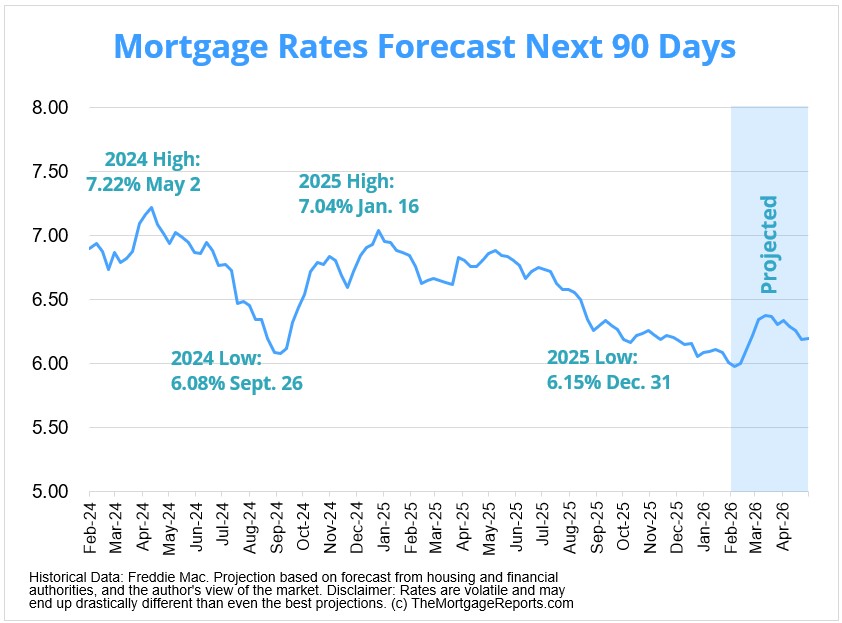
Mortgage interest rates forecast next 90 days
One FOMC meeting falls within the next 90 days: December 8-9, 2026. The Fed held the target range at 3-3/4 to 4 percent at the October 27-28 meeting on a 10-2 vote, and markets will spend the next six weeks recalibrating expectations for the December decision based on incoming data.
The CPI release on November 12 and the PCE release on November 25 both land before the December meeting, which means both reports can inform that decision. Softer readings would support the case for a cut and could pull mortgage rates lower before year-end. Firmer prints would reinforce the hold and keep rates near current levels.
Find your lowest mortgage rate. Start hereBorrowers should also watch the 10-year Treasury yield, which has moved into the 5% zone according to recent market commentary. Mortgage rates track the 10-year closely, so any sustained move in the Treasury should pull the 30-year fixed with it.
Mortgage rate predictions for November 2026
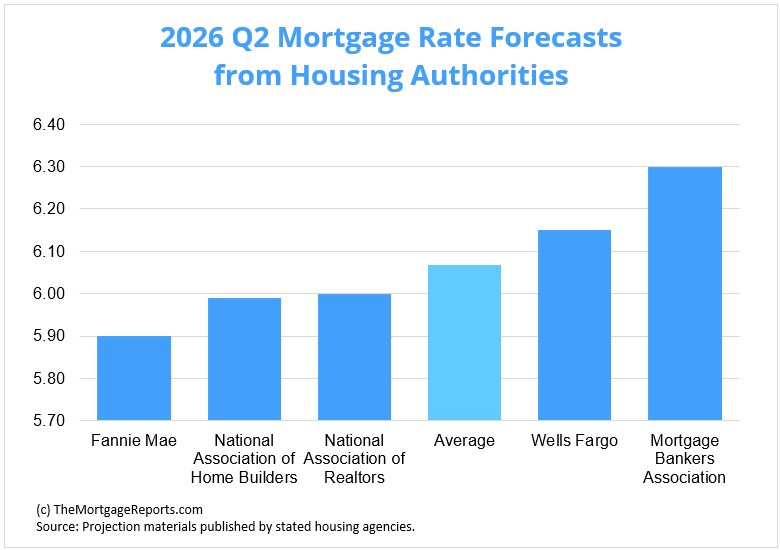
The major housing authorities’ Q4 2026 quarterly-average forecast comes in at 7.350%, with Fannie Mae at the high end at 7.40% and the Mortgage Bankers Association at the low end at 7.30%. These are quarterly averages for Q4 2026, not November monthly figures.
With the current PMMS reading at 7.24%, actual rates are tracking slightly below the Q4 2026 authority average. If November CPI and PCE come in soft and the Fed signals a December cut, we could see rates continue to drift lower. A firmer inflation print would likely push rates back toward the 7.35% consensus.
| Housing Authority | 30-Year Mortgage Rate Forecast (Q4 2026) |
| Mortgage Bankers Association | 7.30% |
| Fannie Mae | 7.40% |
| Average Prediction | 7.350% |
Current mortgage interest rate trends
Freddie Mac’s PMMS put the 30-year fixed at 7.24% for the week ending 10/29/2026, down from 7.32% the prior week. The 15-year fixed came in at 6.6%.
Compared to recent reference points, the 30-year sits at 7.24% today versus 7.32% one week ago, 7.03% four weeks ago, 6.58% three months ago, and 6.19% one year ago. Rates have moved higher over the past month, past quarter, and past year, despite this week’s small decline.
The 14-month history shows rates spent late 2025 and the first quarter of 2026 in the low 6% range, bottoming at 6.05% in February 2026. That marked the low point of the cycle.
| Month | Monthly Average 30-Year Fixed Rate |
| September 2025 | 6.35% |
| October 2025 | 6.25% |
| November 2025 | 6.24% |
| December 2025 | 6.19% |
| January 2026 (partial) | 6.10% |
| February 2026 | 6.05% |
| March 2026 | 6.18% |
| April 2026 | 6.33% |
| May 2026 | 6.44% |
| June 2026 | 6.49% |
| July 2026 | 6.54% |
| August 2026 | 6.67% |
| September 2026 | 6.86% |
| October 2026 (partial) | 7.35% |
Source: Freddie Mac
From March 2026 onward, rates climbed steadily month by month, from 6.18% in March to 6.86% in September and 7.35% in partial October data. The current 7.24% PMMS reading represents a small pullback from that October peak.
The move from 6.19% a year ago to 7.24% today reflects about 105 basis points of upward drift. Over the past three months alone, the 30-year has risen roughly 66 basis points from 6.58%.
Whether rates continue drifting lower from here or stall out depends heavily on the November inflation reports and the December FOMC decision. The near-term direction is more likely sideways to modestly lower than a decisive break in either direction.
Mortgage rate forecast by loan type
Loan-type trends were mixed this week, with 30-year fixed at 7.24% and 15-year fixed at 6.60%.
Find your lowest mortgage rate. Start here30-year fixed
The 30-year fixed averaged 6.66% in Freddie Mac’s August 27 survey. It remains the most common choice for buyers who want a predictable payment spread over a long term.
If you plan to stay in the home for many years, the stability of a fixed payment can be worth the higher rate compared with shorter terms. Compare offers from several lenders before you commit.
The 15-year fixed averaged 5.98% in the same survey, below the 30-year rate. The tradeoff is a higher monthly payment in exchange for less interest paid over the life of the loan.
This term can suit borrowers with room in their budget who want to build equity faster. Run the numbers on the monthly payment before deciding.
Jumbo loans exceed conforming loan limits and often carry different pricing than standard loans. Lenders may apply stricter credit and reserve requirements.
If you are financing a higher-priced home, request quotes specific to jumbo programs. Pricing can differ meaningfully from lender to lender.
Mortgage rate strategies for November 2026
With the 30-year at 7.24% and no FOMC meeting in November, the month looks like a window for careful shopping rather than dramatic market moves. The next policy catalyst sits on December 8-9.
Find your lowest mortgage rate. Start hereThat leaves the November 12 CPI and November 25 PCE releases as the two most important dates for rate watchers this month. Both have the potential to move rates meaningfully in either direction.
Borrowers who find a quote they can afford should weigh locking against the risk that softer inflation data pulls rates lower in late November or December.
Rate locks typically run 30, 45, or 60 days. If your closing is more than 30 days out, a longer lock with a float-down option can give you protection while leaving room to capture a lower rate if the market moves your way.
Rate lock strategy
Ask each lender about float-down policies, extension fees, and what happens if your closing is delayed. Terms vary widely.
Refinancing math works best when your new rate is meaningfully lower than your current rate and you plan to stay in the home long enough to recoup closing costs. At 7.24%, borrowers who took out loans at the recent cycle lows in early 2026 are unlikely to see a refinance benefit today.
Borrowers who closed at higher rates during the summer and early fall should run the breakeven numbers and watch for any further declines.
Lawrence Yun, Chief Economist at the National Association of Realtors, pointed to recent softness in home sales:
Slower sales often give buyers more room to negotiate on price, inspection repairs, and seller concessions. Lisa Sturtevant of Bright MLS noted that slightly lower rates combined with slower price growth could improve affordability.
Refinance timing
Get pre-approved before shopping | Compare quotes from at least three lenders | Ask about seller-paid rate buydowns | Factor in property taxes and insurance when budgeting | Keep your closing timeline flexible if possible
Buyers who are financially ready should not wait for a specific rate target. The right time to buy depends more on your personal finances and local market conditions than on hitting a particular interest rate.
For a longer view of rate history, see our 30-year mortgage rates chart.
A higher credit score translates directly into a better mortgage rate. Pulling your credit reports 60 to 90 days before applying gives you time to dispute errors and pay down balances.
Home buying strategy
Keep credit card utilization under 30% of limits, avoid opening new accounts in the months before applying, and keep older accounts open to preserve credit history length.
Combine strong credit with multiple lender quotes to put yourself in the best position this month.
- Your credit score and credit history
- Your personal finances
- Your down payment (if buying a home)
- Your home equity (if refinancing)
- Your loan-to-value ratio (LTV)
- Your debt-to-income ratio (DTI)
To figure out what rate a lender can offer you based on those factors, you have to fill out a loan application. Lenders will check your credit and verify your income and debts, then give you a ‘real’ rate quote based on your financial situation.
You should get three to five of these quotes at a minimum, then compare them to find the best offer. Look for the lowest rate, but also pay attention to your annual percentage rate (APR), estimated closing costs, and ‘discount points’ — extra fees charged upfront to lower your rate.
This might sound like a lot of work. But you can shop for mortgage rates in under a day if you put your mind to it. And shaving just a few basis points off your rate can save you thousands.
Compare mortgage and refinance rates. Start here
Mortgage interest rate FAQ
What are today’s mortgage rates?
Mortgage rates are rising, but borrowers can almost always find a better deal by shopping around. Connect with a mortgage lender to find out exactly what rate you qualify for.
Time to make a move? Let us find the right mortgage for you1Today's mortgage rates are based on a daily survey of select lending partners of The Mortgage Reports. Interest rates shown here assume a credit score of 740. See our full loan assumptions here.
Selected sources:
- https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
- http://www.freddiemac.com/research/datasets/refinance-stats/index.page